
Your First Home Government Scheme announced
28 Sep, 2026
Buying your first home is about more than saving a deposit. You also need to understand what you can afford, how much a lender may offer, what fees and taxes apply, and what legal checks protect you before you commit.
The Government’s newly announced Your First Home scheme could make buying more accessible for some first-time buyers in England, but the final rules have not yet been published.
The Government says further details will be confirmed at the Budget on 28 October 2026.
What is the Your First Home scheme?
Based on the announcement so far, the scheme is expected to offer:
- A buyer deposit from 2.5%
- A 20% Government-backed equity loan
- A reduced mortgage requirement
- Access to qualifying new-build homes
- Household income limits
- Local property-price caps
- Participation by approved developers
The equity loan is also expected to have an initial interest-free period, although the detailed repayment terms and future charges are still to be confirmed.
How could it help you get onto the Property Ladder?
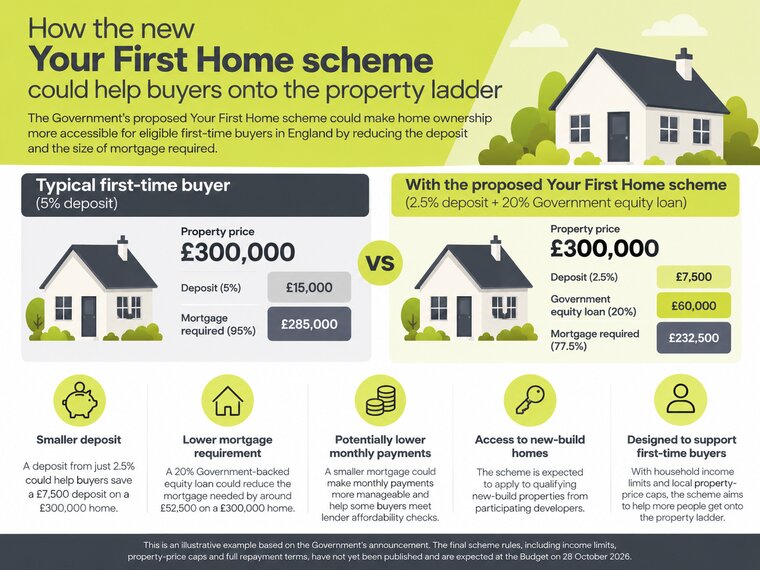
On a £300,000 home, a standard 5% deposit would be £15,000.
Under the proposed Your First Home structure:
2.5% deposit: £7,500
20% equity loan: £60,000
Mortgage required: around £232,500
In this example, the buyer would need £7,500 less upfront and would borrow £52,500 less through their mortgage.
That could make monthly payments more manageable and potentially help some buyers meet lender affordability requirements.
However, the equity loan is still a financial commitment, so the final repayment rules will be important.
What first-time buyers should know
Before buying, make sure you:
- Work out what you can comfortably afford, not just the maximum a lender may offer.
- Get a mortgage Agreement in Principle before making serious offers.
- Budget for legal fees, surveys, mortgage fees, insurance, removals and repairs as well as the deposit.
- Check your credit history before applying for a mortgage.
- Understand that a lender’s valuation is not the same as an independent property survey.
- Check whether the property is freehold or leasehold and, if leasehold, review service charges, lease length and planned major works.
- Remember that an accepted offer is not normally legally binding in England until contracts are exchanged.
Stamp Duty for first-time buyers
Eligible first-time buyers in England currently pay:
0% on the first £300,000
5% on the portion between £300,001 and £500,000
First-Time Buyers’ Relief is not available if the property costs more than £500,000.
What about a Lifetime ISA?
A Lifetime ISA can also help eligible first-time buyers save for a deposit.
Under the current rules, the property must cost £450,000 or less and other qualifying conditions apply.
How Lifetime ISAs will interact with Your First Home should become clearer once the final scheme rules are published.
What still needs to be confirmed?
Before relying on the scheme, buyers should check:
- The household income cap
- Local property-price limits
- Which developers and lenders will participate
- How long the equity loan is interest-free
- What charges apply afterwards
- How and when the equity loan must be repaid
- Whether the amount owed changes if the property rises in value
- How the scheme works when selling or remortgaging
The bottom line
Your First Home could reduce two major barriers for first-time buyers: the size of the deposit and the amount that needs to be borrowed through a mortgage.
But buyers should wait for the final rules before making financial decisions based on the scheme.
Further details are expected at the Budget on 28 October 2026.
Sources
UK Government – Your First Home announcement
https://www.gov.uk/government/news/new-first-time-buyer-scheme-to-be-confirmed-at-budget
HM Treasury – Budget 2026 date
https://www.gov.uk/government/publications/chancellor-letter-to-the-treasury-select-committee-tsc-budget-2026-date
MoneyHelper – First-time buyer guidance
https://www.moneyhelper.org.uk/en/homes/buying-a-home/first-time-buyer-money-tips
HMRC – First-Time Buyers’ Stamp Duty Relief
https://www.gov.uk/guidance/stamp-duty-land-tax-relief-for-land-or-property-transactions
UK Government – Lifetime ISA rules
https://www.gov.uk/lifetime-isa/withdrawing-money-from-your-lifetime-isa
*Important: This article is general information only and is not mortgage, financial, tax or legal advice. Your First Home has been announced but its final rules have not yet been published.